

MoneyLion: Banking & Cash Back
by MoneyLion Inc.
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
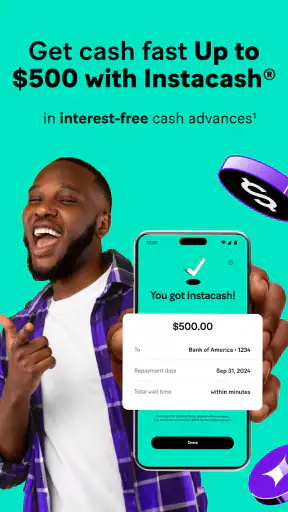
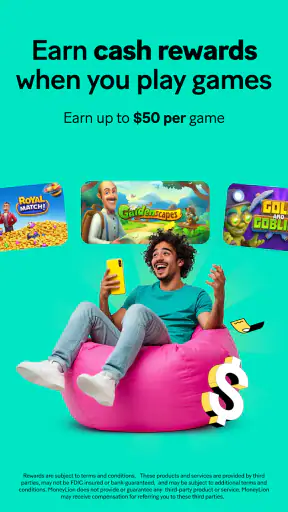
 Analysis by Getfullapps
I approached MoneyLion as a practical finance app rather than as a replacement for every banking tool on my phone. Its appeal is the way it gathers several money-related services in one place: banking features, cash-back opportunities, cash advances, and personal-loan offers. That combination can be useful when I want a single dashboard for everyday money tasks, but it also means I need to read the details carefully instead of treating every option as equally valuable.
Developed by MoneyLion Inc., this free finance app is aimed at adults who want more flexibility around spending and short-term cash flow. It has built a substantial audience, with a 4.5 average from around 218 thousand ratings and more than 5 million installs. Those figures suggest that it is not a niche experiment, but popularity alone is not a reason to connect financial accounts or accept an offer. My main conclusion is straightforward: MoneyLion is most useful as a financial toolbox, especially for people who want to compare available choices in one app, while cautious users may prefer a simpler bank app or a dedicated budgeting service.
How the app feels in everyday use
The first thing I noticed is that MoneyLion is organized around action. Instead of presenting itself only as a place to check a balance, it puts attention on ways to manage spending, access cash, and discover financial products. That makes the app feel more active than a conventional mobile banking application. I can imagine opening it when I am trying to decide whether a short-term cash advance is appropriate, looking for a cash-back opportunity, or reviewing a loan offer alongside my normal banking activity.
That breadth is also the central trade-off. A focused checking app usually has a narrower purpose and therefore a calmer interface. MoneyLion asks me to think about several financial decisions at once. For a user who enjoys comparing choices, this can be convenient. For someone already worried about bills, the number of available paths may feel distracting. I would use the app with a specific goal in mind rather than browsing every offer casually.
The banking side is most helpful when it becomes part of a routine. I would check incoming money, review recent spending, and then look at the other sections only if they solve a current problem. This order matters because it keeps the account view at the center instead of turning borrowing or shopping rewards into the main event. In my experience, a finance app is easier to use responsibly when I decide what I need before I open the promotional areas.
Cash back is more useful when treated as a bonus
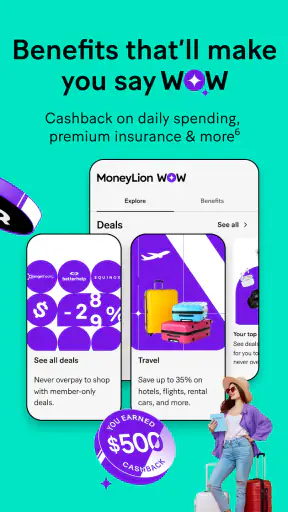
The cash-back element can make MoneyLion attractive to people who already shop through participating offers. The important mindset is not to buy something merely because a reward appears. I would first decide whether the purchase belongs in my budget, then check whether the app offers a relevant benefit. That small change in workflow prevents a discount from becoming an excuse for unnecessary spending.
A practical approach is to use the app before a planned purchase, not after it. If I am replacing a household item or ordering something I already intended to buy, checking the available cash-back section may be worthwhile. I would also keep my receipts or order confirmations until the reward is clearly reflected, because reward systems can involve conditions, timing, or exclusions that are easy to overlook. The app makes finding opportunities convenient, but it does not remove the need to read each offer.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is one area where MoneyLion differs from a basic bank app. A traditional banking application may show the transaction clearly but usually does not make shopping rewards part of the same financial experience. On the other hand, a dedicated cash-back service may be easier to understand if rewards are the only thing I care about. MoneyLion sits between those approaches: broader than a reward app, but not necessarily as specialized as one.
Cash advances require a deliberate decision
The fast-cash option is likely to attract people facing an immediate gap between income and expenses. I can understand the appeal when a bill arrives before payday, but I would treat this feature as a last-resort bridge rather than as extra income. The right question is not simply “Can I access money now?” It is “What will make next week easier if I use this today?”
Before accepting a cash advance, I would review the complete repayment information shown in the app, including any applicable charges, timing, and effect on my upcoming budget. I would then write down the repayment date and reduce optional spending until the balance is settled. This is a concrete advantage of using a finance dashboard: I can check the surrounding money picture instead of making the decision in isolation.
The weakness is that speed can encourage impulse. When I am stressed, a prominent access-to-cash button feels like a solution before I have calculated the consequences. MoneyLion is therefore better suited to someone who can pause, compare the terms, and repay on schedule. If I regularly need advances to cover ordinary living costs, I would choose a budgeting conversation, a spending reduction plan, or a different form of financial support instead of making repeated advances part of my routine.
Loan offers are for comparison, not automatic approval
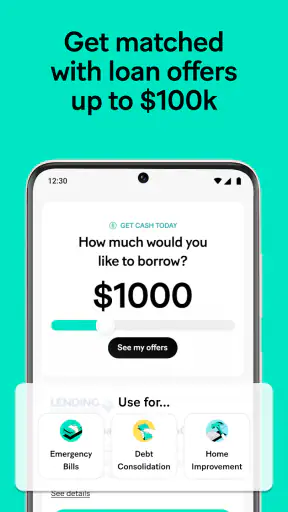
The personal-loan area can save time by bringing offers into the same app, but I would not assume that an offer is the best option simply because it is convenient to access. I would compare the total repayment amount, the rate, the payment schedule, and any fees with alternatives from my bank or a credit union. A lower monthly payment can still cost more overall if the repayment period is longer.
One useful workflow is to decide the maximum amount I can comfortably repay before reviewing offers. That keeps the available amount from setting my budget for me. I would also avoid submitting applications just to satisfy curiosity, particularly when I am not ready to borrow. The strongest value here is organization and comparison; the app should help me make a decision, not make the decision on my behalf.
This is another point where the app is different from a standard bank. A bank application may make an existing relationship feel familiar, while MoneyLion can be useful for seeing financial options in a broader context. Yet familiarity can be valuable too. If my bank already provides a competitive, transparent loan with terms I understand, moving elsewhere only for convenience may not be worthwhile.
What I would do with the app on a normal week
Imagine I have regular income, a few recurring bills, and a planned purchase coming up. I would begin by checking my available balance and recent activity. Next, I would look at cash-back opportunities only for the purchase already in my plan. If an unexpected bill created a shortfall, I would inspect the cash-advance details and compare the repayment date with my next income. I would not open a loan offer unless the expense were larger and I had already calculated a sustainable payment.
At the end of the week, I would review what actually happened rather than focusing on the most attractive offer. Did the reward relate to something I needed? Did borrowing solve a one-time timing issue or hide a recurring budget problem? This habit turns MoneyLion from a menu of financial products into a tool for making better decisions. The app cannot supply discipline, but its combined view can support it when I use it intentionally.
Small habits that make the experience safer
- Separate convenience from value: I would compare the full cost of any advance or loan with outside options, even when the in-app process feels faster.
- Use cash back only on planned spending: A reward is useful when it follows a purchase I already wanted, not when it creates one.
- Keep a repayment reminder: After using short-term cash, I would record the expected repayment and check my next budget before spending freely.
- Review offers with a fixed borrowing limit: I would choose the payment I can afford first and then see whether an available offer fits it.
- Keep the app focused: I would open it for a defined task so that financial promotions do not replace basic balance and spending checks.
The meaningful limitations
My biggest reservation is not that MoneyLion offers several services; it is that those services can blur the line between managing money and seeking more money. Banking, rewards, advances, and loans have very different consequences. Putting them together is convenient, but it requires more attention from me than a straightforward account app would.
I also would not choose it as my only financial system if I need detailed planning, investment analysis, or a highly specialized budgeting experience. The app’s strength is the combination of everyday banking and access to financial options. Someone who wants deep category-based budgeting may be happier with a dedicated budgeting application, while someone who only needs deposits and payments may prefer a simpler bank interface.
There is also a personal suitability question. Users with predictable income and occasional timing problems may find the cash tools practical. Users with unstable income, persistent debt, or difficulty resisting credit offers should be more cautious. The more often I need borrowed money for ordinary expenses, the less useful the app’s convenience becomes. In that situation, the right alternative is not necessarily another finance app; it may be a service that focuses on debt management, counseling, or a realistic spending plan.
Privacy and account access deserve the same attention as the financial terms. I would read the permission and connection screens carefully, use a strong device lock, and avoid signing in on a shared phone. I would also review notifications so that urgent-sounding prompts do not push me into a rushed decision. These are not reasons to reject the app, but they are sensible habits for any service handling banking information.
Who will get the most from it
I think MoneyLion fits people who want several financial tools in one mobile experience and are comfortable comparing terms before acting. It is especially practical for someone who wants to check banking activity, investigate planned cash-back purchases, and keep short-term borrowing options nearby without switching between multiple services. The free price makes it easy to try, and the Everyone age rating gives it a broad audience, although responsible use still depends on the individual’s financial situation.
It is less suitable for a person who wants a quiet, no-distraction banking app. It is also not my first recommendation for someone who sees available credit as spending power, or for anyone who is looking for a complete financial plan rather than a collection of tools. In those cases, a conventional bank, a focused budgeting app, or a human adviser may provide clearer boundaries.
The app has been available since May 19, 2016, and its current version is 7.158.0, with support beginning at Android 7.0. Those details matter when deciding whether an older phone can run it, but I would still keep the operating system updated for security and compatibility. The application is free to install, yet free access should not be confused with every financial option being cost-free; I would inspect the terms attached to each service separately.
My final recommendation
MoneyLion works best when I treat it as a decision-support toolbox, not as a shortcut around budgeting. Its strongest evidence is the useful combination of banking, cash back, fast-cash access, and personal-loan offers in one finance app. That can reduce friction for everyday money management and make it easier to compare choices at the moment I need them.
Its main weakness is the same feature that makes it appealing: the app puts borrowing and rewards close to ordinary banking. I need to stay alert, read the details, and avoid turning temporary access to cash into a recurring habit. If I can do that, the convenience is meaningful. If I want only basic banking or I know that prominent credit options will tempt me, I would choose a more focused alternative.
Overall, I would recommend MoneyLion to a financially organized user who wants flexibility and is willing to make careful comparisons. I would suggest starting with routine balance checks and planned cash-back use, then considering advances or loan offers only when the repayment plan is already clear. Used that way, MoneyLion is a capable companion for everyday financial decisions, provided I remain the one setting the limits.
Pros
- Early direct-deposit access can make paychecks available sooner.
- Cash-back rewards add value when shopping through eligible offers.
- Credit-building tools may help users establish a stronger credit profile.
- In-app budgeting features make it easier to monitor spending habits.
- A broad range of financial tools is available in one mobile app.
Cons
- Some features require a paid membership or recurring subscription.
- Reward rates and offer availability can change over time.
- Cash advances may include optional fees or expedited-transfer charges.
- Loan and credit products depend on eligibility and approval terms.
- The app may request extensive personal and financial information.
FAQs for MoneyLion: Banking & Cash Back
What is MoneyLion: Banking & Cash Back?
MoneyLion is a personal finance app that combines several money-management services in one place. Depending on your eligibility and location, it may offer spending and banking features, cash-back rewards, credit monitoring, budgeting tools, earned-wage access, and lending-related products. The exact features available can vary by user, so it is worth reviewing the current terms, fees, and eligibility requirements before opening an account.
Is MoneyLion: Banking & Cash Back free to use?
MoneyLion can be downloaded without paying an upfront fee, but not every feature is necessarily free. Some optional products, memberships, instant-transfer services, advances, or credit-building tools may involve charges, subscription costs, or other conditions. Before confirming a transaction, carefully check the displayed pricing, recurring-payment details, repayment terms, and applicable disclosures so you understand the total cost.
Can I use MoneyLion to receive my paycheck and manage everyday spending?
The app may provide an account and related spending features that allow eligible users to receive direct deposits, track transactions, transfer funds, and use an associated debit card or virtual card. Availability can depend on identity verification, location, account status, and current product rules. It should not automatically be treated like a traditional bank account without checking the applicable banking and deposit terms.
How does MoneyLion cash back work?
MoneyLion’s cash-back opportunities may be connected to eligible purchases, participating merchants, offers, or specific products inside the app. Rewards are usually subject to activation requirements, qualifying transactions, exclusions, minimums, and redemption rules. Because offers can change, users should read each promotion carefully, confirm that a purchase qualifies, and check when and how the reward will be credited.
Is MoneyLion safe, and what information is needed to sign up?
MoneyLion uses account-security measures and identity verification procedures, but no financial app can eliminate every security or privacy risk. Registration may require personal details, contact information, identity documents, and permission to connect financial accounts, depending on the services selected. Use a strong password, enable available security protections, review privacy permissions, and download the app only from an official store.

MoneyLion: Banking & Cash Back
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@moneylion.com, visit https://www.moneylion.com, or review their https://www.moneylion.com/privacy-notice/.










